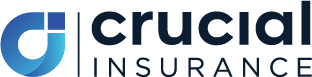
The insurance that protected your business five years ago may no longer provide the protection you need today. As your organisation expands, acquires valuable assets, opens new locations or becomes more dependent on specialised equipment, the financial consequences of a major loss can become considerably more complicated.
For many Australian businesses, a general or packaged “Business Insurance” policy, or a “Business Pack Insurance” policy is an effective way to manage everyday commercial risks. However, as your operations become larger or more complex, there may come a point when the limitations of a standard insurance package deserve closer examination.
This is where Industrial Special Risks (ISR) Insurance comes in. Designed for organisations with substantial physical assets and more complex exposures, ISR can offer broader, more flexible protection against property damage and the financial consequences of business interruption.
But does that mean ISR Insurance is always the better choice? Not necessarily. Understanding the differences can help you decide whether your existing arrangements remain appropriate or whether your business would benefit from a more tailored approach.
What Is the Difference Between ISR and Business Pack Insurance?
Both Industrial Special Risks Insurance and Business Insurance Packages can protect businesses against property damage and the financial consequences of certain unexpected events. However, they generally differ in how coverage is structured and the types of businesses they are designed to protect.
Business Pack Insurance
Business Pack Insurance is typically designed for small to medium-sized businesses that require protection against a range of common commercial risks.
Rather than arranging multiple individual policies, businesses can combine various forms of insurance within a single package. Depending on the insurer and selected sections, this may include property damage, theft, glass, Business Interruption Insurance, Public Liability Insurance and equipment breakdown.
The main advantage is convenience. Businesses can select relevant forms of protection without necessarily requiring a highly customised property insurance arrangement.
However, Business Pack policies generally operate through specified sections of cover, with particular insured events, definitions, limits and exclusions determining when a claim may be paid.
Industrial Special Risks Insurance
ISR Insurance is generally designed for medium to large organisations with significant property values, multiple locations or operational risks that require more tailored protection.
Unlike many standard Business Pack policies, ISR is commonly written on an “all risks” basis, meaning physical loss or damage to insured property may be covered unless specifically excluded by the policy.
This distinction can be important for businesses with complex operations, unusual assets or substantial financial exposure to unexpected events.
According to the Insurance Council of Australia’s February 2026 submission on ISR and Business Interruption Insurance, ISR policies can generally offer broader and more flexible coverage arrangements, including greater opportunities to tailor policy conditions to individual business requirements.
However, broader coverage does not mean every event is insured. ISR policies still contain exclusions, conditions, deductibles and limits that need careful consideration.
Five Reasons to Choose ISR Over Business Pack Insurance
1. Broader Protection Against Unexpected Property Damage
One of the biggest potential advantages of ISR Insurance is the way property damage coverage is structured. Business Pack policies generally insure property against specific events or categories of loss, although some provide additional accidental damage protection.
ISR policies typically take a broader approach by covering physical loss or damage unless an exclusion applies.
For example, a business may experience an unusual form of accidental damage involving its premises or equipment. If the event falls outside the insured risks defined in its Business Pack policy, the loss may not be covered.
Under an ISR arrangement, that same event may potentially be insured if it falls within the policy’s broad insuring clause and is not otherwise excluded.
This can reduce the risk of certain unexpected events falling outside the scope of cover. However, the actual outcome will always depend on the policy wording and circumstances of the loss.
Why this matters: The more complicated your business operations become, the harder it may be to anticipate every possible cause of physical damage.
2. More Flexibility for Large or Complex Businesses
Standard Business Pack Insurance can offer considerable flexibility, but insurers may impose restrictions around the values, industries, locations or types of assets they are prepared to insure.
ISR Insurance is designed to accommodate more complex property exposures and can often be negotiated around the specific needs of an organisation.
This can be especially valuable if your business operates multiple facilities, owns specialised equipment or has significant stock holdings.
For example, a manufacturing business might operate two production facilities, a distribution warehouse and an administrative office. Each location could have different asset values, activities and exposure to natural disasters.
Rather than relying on standard packaged property coverage, an ISR policy may allow the organisation to negotiate arrangements that better reflect the risks associated with each location.
This flexibility can extend to policy limits, specific extensions, deductibles and certain exclusions.
The key advantage is not simply having a larger insurance policy. It is having greater scope to structure the protection around how your business actually operates.
3. More Tailored Protection Against Business Interruption
A major property loss can create financial problems that continue long after the initial damage occurs. While a building might eventually be repaired or damaged equipment replaced, restoring business operations can take significantly longer.
During that period, your organisation may continue facing expenses while revenue remains below normal levels.
Both Business Pack and ISR policies can include Business Interruption Insurance. However, ISR arrangements may provide greater flexibility when addressing complex business interruption exposures.
Depending on the policy, this can involve negotiating protection for lost gross profit, additional operating expenses and certain interruptions caused by damage at suppliers’ or customers’ premises.
Consider a manufacturer that relies on a specialised piece of equipment imported from overseas.
If a fire destroys that equipment, replacing it may take several months. Even after the replacement arrives, the business could face additional delays while it is installed, tested and brought back into production.
Having insurance for the physical damage is important, but the resulting interruption to revenue could prove equally significant.
An appropriately structured ISR policy may help address these financial consequences, provided the relevant damage and interruption are insured.
The important consideration is whether your policy’s indemnity period reflects how long your business could realistically take to recover.
An indemnity period that is too short may leave your organisation exposed even where the initial property damage is insured.
4. Greater Capacity for High-Value Assets
The value of your assets can also influence whether ISR Insurance is appropriate.
As your organisation grows, the combined replacement cost of buildings, machinery, equipment and stock may become substantial.
While Business Pack Insurance can accommodate significant property values, some insurers impose underwriting limits or restrictions that make these policies less suitable for larger exposures.
ISR policies are commonly used for organisations requiring higher limits or more complicated insurance arrangements.
The Insurance Council of Australia identifies businesses with more than $10 million in assets as typical candidates for ISR, although it emphasises that there is no universal threshold determining which policy is appropriate.
Consequently, a business with less than $10 million in assets may still benefit from ISR if its operations are sufficiently complex. Conversely, a larger organisation with relatively straightforward exposures may find that a Business Pack remains suitable.
Asset values are therefore an important consideration, but they should never be the only factor influencing your decision.
5. Better Opportunities to Address Specific Operational Risks
As businesses grow, their insurance requirements often become more specialised. A manufacturer may rely on expensive production machinery, while a logistics operator may have substantial stock concentrated across several warehouses. A commercial property owner, meanwhile, could face significant rental income losses following major damage to a building.
These exposures may require policy conditions or extensions that go beyond what is readily available under a standard Business Pack. ISR Insurance can provide greater opportunities to negotiate protection for specific property and business interruption risks.
However, it is important to recognise that some exposures still require additional insurance arrangements.
For example, Machinery Breakdown Insurance may be needed to address mechanical or electrical breakdowns that are excluded under an ISR policy. Similarly, Cyber Insurance should be considered separately where your business faces significant financial exposure to ransomware, data breaches or other cyber incidents.
ISR Insurance is primarily designed around property damage and associated business interruption. It is not a replacement for every other form of commercial insurance your organisation may need.
When Might Business Pack Insurance Be the Better Choice?
Despite the potential advantages of ISR, general Business Insurance policy or Business Pack Insurance remains an effective option for many Australian businesses.
In fact, moving to ISR unnecessarily could introduce additional costs and administrative complexity without delivering meaningful improvements in protection.
A Business Pack may remain appropriate if your organisation has relatively straightforward operations, modest property values and insurance requirements that can be addressed through standard policy sections.
For example, a professional services firm operating from a single office may require cover for contents, electronic equipment, liability and certain business interruption exposures.
A carefully selected Business Pack could provide an effective combination of these protections without requiring a separate ISR arrangement.
Business Pack policies may also include insurance sections that are not ordinarily part of ISR, particularly liability-related protections.
Therefore, switching from a Business Pack to ISR without reviewing the entire insurance program could unintentionally remove important coverage.
The objective should not be to obtain the most comprehensive-looking policy. It should be to obtain the insurance that best addresses the risks your business faces.
Is ISR Insurance More Expensive Than Business Pack Insurance?
ISR Insurance can be more expensive than a Business Pack policy, particularly where it provides broader coverage, higher limits or protection for complex risks.
The underwriting process may also be more involved. Insurers could require detailed information about your properties, operations, asset values, fire protection systems, claims history and business interruption exposures.
However, comparing premiums alone can be misleading. A lower premium may appear attractive, but it becomes less valuable if the policy contains restrictions that leave your organisation facing a substantial uninsured loss.
Likewise, paying more for ISR Insurance does not automatically mean your business is receiving better protection. The most meaningful comparison considers the scope of cover, limits, exclusions, deductibles and potential financial consequences of an uninsured event.
An experienced broker can help you evaluate these differences rather than simply comparing the prices quoted by insurers.
How Do You Know When It Is Time to Switch to ISR?
There is no single point at which every organisation should move from a Business Pack to ISR Insurance.
However, changes to your operations can indicate that your existing policy deserves closer examination.
Some questions worth considering include:
- Have your asset values increased significantly? New premises, equipment, infrastructure or stock may have increased the potential cost of a major loss.
- Are you operating across multiple locations? Different properties may introduce additional exposures that require more tailored arrangements.
- Could an insured event interrupt operations for several months? Complex production processes or long equipment replacement periods may require a more detailed business interruption assessment.
- Does your current policy contain restrictive limits or exclusions? These may become more significant as the financial consequences of a loss increase.
- Have you entered new industries or changed your operations? Activities that differ from those originally disclosed to your insurer could affect the suitability of your existing policy.
- Are you struggling to obtain appropriate cover under a standard Business Pack? This could indicate that your organisation requires access to more specialised insurance arrangements.
If several of these circumstances apply, it may be worth discussing ISR Insurance with your broker before your next renewal.
The Australian Government recommends reviewing business insurance whenever your circumstances change, rather than relying on an existing policy to remain appropriate indefinitely.
What Should You Review Before Moving to ISR Insurance?
Changing insurance arrangements requires more than selecting a different type of policy.
Before making the switch, your business should evaluate how the proposed ISR coverage compares with its current protection.
Property values and underinsurance
Accurate asset valuations are essential, regardless of the type of insurance you purchase. Underinsurance can create significant problems during claims, particularly where a policy contains an averaging or co-insurance provision.
These provisions can reduce the amount payable when insured property values are lower than the amounts required under the policy.
In March 2026, the Insurance Council of Australia and National Insurance Brokers Association published a joint fact sheet explaining how averaging provisions can affect business insurance claims.
The fact sheet highlights why businesses should regularly reassess their insured values, particularly after purchasing new equipment, renovating premises or expanding operations.
Business interruption requirements
Your business should also review the financial impact of a prolonged interruption to operations.
This involves assessing your gross profit, ongoing expenses, recovery timelines and the dependencies that could delay a return to normal trading. A larger indemnity period may be appropriate where rebuilding facilities, sourcing specialised machinery or restoring production could take considerable time.
However, the right period and insured amounts depend on your particular circumstances.
Exclusions, deductibles and additional coverage
While ISR policies can offer broader property protection, exclusions still apply.
Areas such as flood, mechanical breakdown, cyber incidents, gradual deterioration and certain forms of contamination may be excluded or subject to specific conditions.
It is also important to identify which sections of your existing Business Pack would no longer be included under the proposed ISR arrangement.
Your broker should assess whether these protections need to be retained through separate policies or additional coverage.
Why an Experienced Insurance Broker Matters
Choosing between ISR and Business Pack Insurance can involve complex decisions that extend well beyond the headline level of cover.
Different insurers may offer substantially different conditions, and even policies described as comprehensive can contain exclusions or limitations that materially affect a claim.
A good insurance broker should take the time to understand your organisation’s operations, financial exposures and future plans before recommending a particular insurance structure.
This includes assessing whether your current policy remains appropriate, identifying potential coverage gaps and negotiating suitable terms with insurers.
For businesses considering ISR, a broker’s experience can be particularly valuable when reviewing complex policy wording, calculating business interruption exposures and arranging protection for substantial or unusual risks.
At Crucial Insurance and Risk Advisors, we work with Australian businesses to understand their risks, compare insurance options and develop arrangements that reflect their individual requirements.
Our focus is not simply on finding insurance. It is on helping your business understand where it is protected, where gaps may exist and how those exposures could affect your financial position.
ISR or Business Pack Insurance: Which Is Right for Your Business?
There is no universal answer to whether ISR Insurance is better than Business Pack Insurance. For smaller organisations with straightforward insurance requirements, a Business Pack may provide effective protection without the additional complexity of a bespoke policy.
For larger businesses with substantial physical assets, multiple locations or significant business interruption exposures, ISR Insurance may offer important advantages through broader and more flexible property coverage.
What matters most is whether your insurance reflects the financial consequences of the risks your organisation faces today.
If your business has grown, changed its operations or accumulated substantial assets, now may be the right time to review whether your existing insurance is still appropriate.
At Crucial Insurance and Risk Advisors, we help Australian businesses assess their insurance arrangements, identify potential gaps and explore suitable protection for complex commercial risks.
Contact Crucial Insurance today to arrange a complimentary insurance review and find out whether ISR Insurance or Business Pack Insurance is the better fit for your organisation.
References
The following sources were consulted when preparing this article. Relevant references have also been linked throughout the content.
- Insurance Council of Australia (2026). Small Business Insurance: Industrial Special Risks Insurance and Business Interruption Insurance. Submission to the Parliamentary Joint Committee on Corporations and Financial Services, 23 February 2026.
- Insurance Council of Australia & National Insurance Brokers Association (2026). Understanding Averaging Provisions: Are You Underinsured? March 2026.
- Australian Government, business.gov.au. Types of Business Insurance.
- Australian Government, business.gov.au. Manage Your Business Insurance.
- Australian Government, business.gov.au. Prepare Your Business for an Emergency.
 This article was written by Tony Venning,
Managing Director at Crucial Insurance and Risk Advisors.
For further information or comment please email info@crucialinsurance.com.au.
Important Disclaimer – Crucial Insurance and Risk Advisors Pty Ltd ABN 93 166 630 511 AFSL 45150. This document provides information rather than financial product or other advice. The content of this document, including any information contained on it, has been prepared without taking into account your objectives, financial situation or needs. You should consider the appropriateness of the information, taking these matters into account, before you act on any information. In particular, you should review the product disclosure statement for any product that the information relates to it before acquiring the product.
Information is current as at the date documents are written as specified within them but is subject to change. Crucial Insurance, its subsidiaries and its associates make no representation as to the accuracy or completeness of the information. All information is subject to copyright and may not be reproduced without the prior written consent of Crucial Insurance.